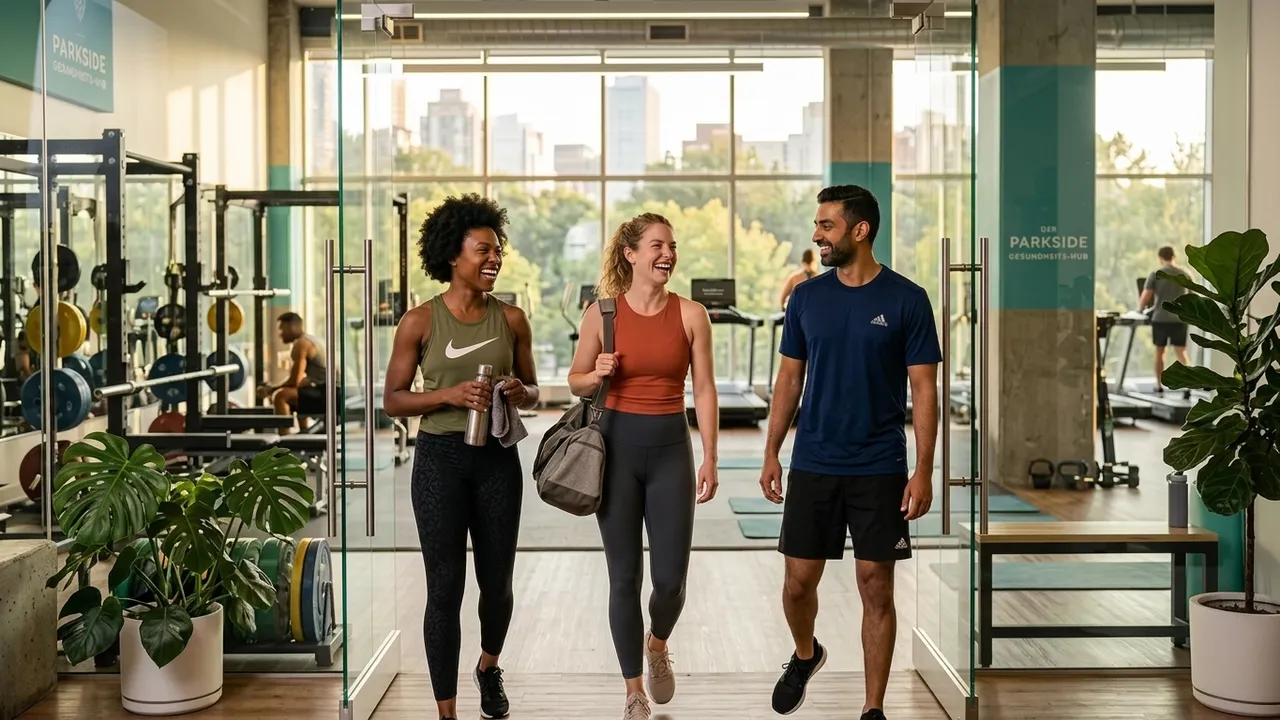
Fitness offerings in companies often fail because they're too far away – in time, distance, or mindset. A partnership with a local studio or a network provider such as Urban Sports Club or Epassi (formerly Hansefit) solves exactly this problem, without the company having to build its own infrastructure. To also reach people who prefer to run, cycle or walk outdoors, add an activity app such as Move Republic.
What sets a good partnership apart from a mediocre benefit?
What matters most is the barrier to first use. Partnerships where employees have to sign their own contract, submit an application, or handle monthly billing are often used less than models with a single registration link and instant access. The best partnerships work like a digital key: set up once, then use without limits. Network providers with many locations are especially suited to hybrid teams who aren't in the same place every day. For tax purposes in Germany, a gym partnership does not fall under the €600 tax allowance (Section 3 No. 34 EStG); it runs via the €50 limit for benefits in kind. Only your tax adviser can confirm this; the guide Insurer funding and the tax allowance gives an overview of the routes.
How do you keep usage rates high from the start?
A partnership agreement is useless if it gathers dust on the intranet. The most powerful marketing tool is personal recommendation: when colleagues talk over lunch about using the studio, that pulls harder than any poster. Targeted kickoff activities – a shared first visit, a short intro session – significantly lower the psychological barrier to entry.
How to put it in place
- 1Shortlist one or two fitness studios within walking distance and ask for corporate rates and the range of classes.
- 2Negotiate discounted memberships without a long commitment and clarify whether a minimum number of participants is required.
- 3Clarify the tax treatment with payroll and your tax adviser: gym fees are not tax-free under § 3 no. 34 EStG (German Income Tax Act; German law). As a benefit in kind, the €50 monthly threshold (Freigrenze, § 8 para. 2 sentence 11 EStG; German law) may apply – then the subsidy must be provided as a benefit in kind, not as money. Document the requirements.
- 4Decide how the subsidy is settled (directly with the studio or as a reimbursement to employees – a reimbursement in cash is not a benefit in kind) and put it in writing.
- 5Inform all employees about the terms, the studio location and how to sign up in a clear short guide.
- 6Provide a simple sign-up/activation process (form or a contact person at the studio).
- 7Explain the tax treatment and the personal contribution transparently so that no questions remain open.
- 8Maintain the participant list and reliably report new joiners and leavers to the studio.
- 9Collect feedback on opening hours, classes and satisfaction once or twice a year.
- 10Stay in touch with the studio so that additional classes (e.g. back school) can be added when needed.
- 11Evaluate the usage rate and satisfaction anonymously and compare them with the costs.
- 12Check whether the €50 threshold is observed (it applies to all benefits in kind of a month taken together) and the documentation is complete.
- 13Decide together with management on renewal, switching studios or expanding the offer.
What you need
- Effort
- half a day
- Cost
- with budget
- Setup
- 480 min
- ✓ Subsidy may be tax-free as a non-cash benefit (€50 limit, not Section 3 No. 34 EStG, German law) – check with your tax advisor
- ✓ Attractiveness
- ✓ Sustainable
Adopt it for your company
One click — and the measure sits ready in your plan. Guided step by step, no lengthy setup.
ÜbernehmenZahlt ein auf
Measure the impact with
Handlungsfeld
Passender Anlass
Passende Best Practices
Nicht sicher, wo ihr anfangen sollt? Selbstcheck →